Market Overview: Defining the Dangerous Goods Bag Market
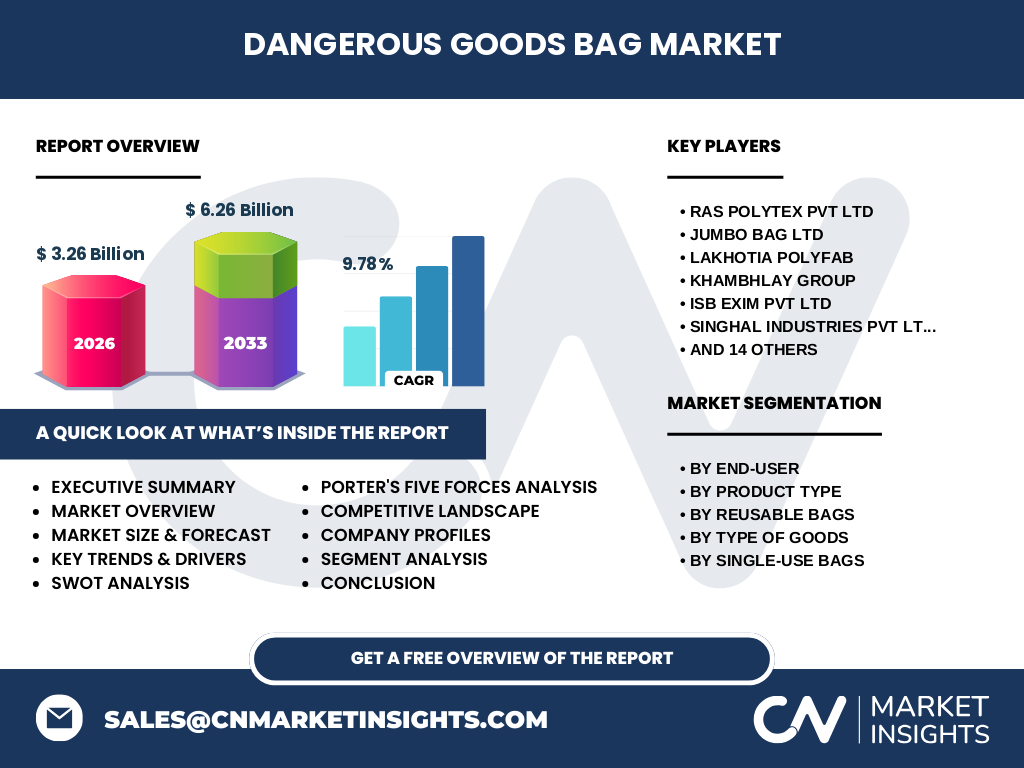
The Dangerous Goods Bag Market encompasses specialized containment solutions engineered for the secure transport of hazardous materials. Valued at 3.26 Billion in 2026, the industry serves as a critical safety buffer for global supply chains. By integrating high-barrier films and UN-certified fabrics, manufacturers ensure compliance with stringent international protocols governing the transit of explosives, flammable liquids, and toxic substances across multimodal transport networks.
Structural Growth Drivers and Market Constraints
Growth is primarily fueled by the 9.78% CAGR projection, driven by rigorous enforcement of IMDG and ADR regulations. However, the market faces significant logistical hurdles, including volatile raw material pricing for high-grade polyethylene and complex cross-border trade barriers. Strategic opportunities lie in the expansion of waste management infrastructure, as global demand for specialized containers for toxic and infectious substances increases in emerging industrial hubs.
Emerging Trends in Dangerous Goods Containment
A pivot toward sustainability is defining the landscape, with manufacturers like Mondi Group and Amcor plc pioneering high-performance biodegradable bags. The market is shifting from traditional single-use polyethylene structures toward advanced composite material bags that offer superior tear resistance. These innovations allow end-users to meet circular economy mandates without compromising the safety integrity required for transporting radioactive or oxidizing materials.
Impact Analysis of COVID-19 and Recovery Trajectory
The pandemic acted as a catalyst for volatility, disrupting supply chains for raw polymers used in FIBCs. While global trade faced bottlenecks, the surge in hazardous waste disposal demand provided a crucial cushion. Current recovery is characterized by a rapid return to pre-pandemic shipment volumes, with companies like Greif Inc leveraging digital supply chain optimization to restore efficiency in delivery timelines for chemical manufacturers.
Competitive Benchmarking and Strategic Dynamics
The market exhibits high concentration, dominated by industrial giants like Berry Global Inc and Smurfit Kappa Group, alongside specialized players like Rishi FIBC. Competition is driven by certification speed—the ability to secure UN-approval for new designs quickly—and the geographic proximity of manufacturing units to major international ports, which reduces lead times for distributors and manufacturers handling flammable solids.
Executive Summary of the Dangerous Goods Bag Market
The sector is on a high-growth trajectory, expanding from a 2026 valuation of 3.26 Billion to a projected 6.26 Billion by 2033. This significant growth reflects the increased sophistication of safety standards across industrial sectors. Our proprietary research emphasizes that companies investing in smart-tracking capabilities and specialized composite bag materials will capture the lion’s share of the market through the next decade.
Market Forecast 2027–2033: What is the path forward?
Our analysis projects that the market will reach 6.26 Billion by 2033. This expansion is supported by a consistent 9.78% CAGR, fueled by urbanization in APAC and strict environmental mandates in Europe. The forecast assumes sustained demand from waste management companies and the critical role of durable packaging in securing the transport of increasingly complex, classified dangerous goods globally.
Market Segmentation: Defining Key Industry Roles
Segmentation is bifurcated into product type and end-user. Single-use bags, including aluminum foil and laminated variants, remain vital for retail and infectious waste, while reusable FIBCs and woven polypropylene structures dominate the manufacturer and distributor segments. This segmentation allows for precise risk management, enabling users to match the specific container chemistry to the classification of dangerous goods being transported, from corrosive substances to flammable liquids.
Regional Market Performance and Distribution
North America and Europe currently hold the largest market share, driven by stringent safety regulations and mature chemical industries. However, the Asia-Pacific region is emerging as a high-growth frontier. The regional performance is highly correlated with the presence of major chemical manufacturing clusters and the efficiency of logistical hubs at primary ports, where the throughput of hazardous materials requires high-volume, compliant bagging solutions.
In-depth Review of Regional Market Dynamics
The Middle East and North Africa (MENA) sector, supported by oil and gas chemical output, shows unique demand for heavy-duty nylon and PVC-coated fabric bags. Conversely, European markets prioritize biodegradable solutions due to local green directives. These regional nuances necessitate that companies like Singhal Industries Pvt Ltd maintain localized production capacities to balance regulatory compliance with cost-effective, regional logistics requirements.
Company Profiles: Strategic Positioning
Major players utilize distinct competitive levers. Sonoco Products Company and WestRock Company focus on vertical integration to secure paper-based supply for their hazardous waste segments. Meanwhile, niche innovators like Khambhlay Group and Ras Polytex PVT LTD differentiate through custom engineering, providing bespoke fabric bags for the explosives and radioactive material sectors where specialized material certification is a significant barrier to entry for smaller competitors.
Porter's Five Forces Analysis of the Competitive Landscape
Competitive rivalry is intense, with high entry barriers due to the necessity for international UN-certification. While the bargaining power of buyers is moderate, the bargaining power of raw material suppliers remains high for specialized high-barrier films. The threat of substitutes is low for core dangerous goods transport, but innovative composite materials are successfully displacing traditional, less durable packaging alternatives across the board.
SWOT Analysis of the Global Dangerous Goods Bag Market
Strengths include the essential nature of the product for safety. Weaknesses involve high regulatory dependence. Opportunities abound in the burgeoning waste management sector, where Hazibag Corporate is leading. Threats are clearly represented by geopolitical instability affecting global shipping routes, which could constrain the supply of specialized polymers, directly impacting the availability of compliant containment bags for explosive and flammable goods globally.
Value Chain Analysis: From Raw Materials to End-Users
The value chain originates with petrochemical feedstock suppliers providing the base resins (PP, PE, PVC). Mid-stream manufacturing involves complex weaving, lamination, and coating processes. Value is captured by the packaging converters who secure the final safety certification. The flow concludes with logistics service providers and industrial end-users, where regulatory compliance ensures the integrity of the value proposition from factory floor to disposal site.
Investment Insights and High-Potential Areas
High-potential investment is gravitating toward smart packaging technology, specifically RFID-integrated FIBCs for hazardous waste monitoring. Investors should target companies that offer end-to-end certification services in emerging markets like India and Southeast Asia. The 9.78% CAGR suggests a robust environment for mergers and acquisitions, particularly for firms seeking to consolidate regional manufacturing footprints with established, globally recognized, and compliant bag product portfolios.
Key Takeaways and Final Industry Conclusion
The Dangerous Goods Bag Market is fundamentally transitioning from a commodity-based sector to a high-value, specialized-engineering industry. Reaching 6.26 Billion by 2033, the market's trajectory is anchored by safety mandates. Key takeaway: competitive advantage will be awarded to players who marry superior material science with flexible, globally-compliant manufacturing footprints, effectively serving the diverse needs of the chemical, radioactive, and waste management end-user categories.
Methodology: Ensuring Data Integrity
Our methodology utilizes triangulation of primary and secondary data. We cross-reference industrial trade registry data with direct interviews from stakeholders at firms like Jumbo Bag Ltd and Lakhotia Polyfab. Macroeconomic indicators, including global chemical output and regulatory updates from international transport agencies, serve as the baseline for our quantitative models, ensuring our 2027–2033 projections remain robust, reflective of real-world supply chain conditions.
Scope of the Report and Coverage Parameters
This report examines the global market for hazardous packaging, focusing on product types (FIBCs, PE, PP, Laminated, Biodegradable) and end-use sectors. Limitations involve regional variances in small-scale local producers, which are omitted for the purpose of maintaining a high-accuracy baseline. The report covers the financial trajectory from 2026 through 2033, analyzing structural trends within the regulatory frameworks of major chemical-producing economies.
Recent Developments in the Dangerous Goods Bag Market
Recent activity highlights a wave of partnerships aimed at enhancing supply chain transparency. Blue Line Industries LLC and FIBC-Silvassa have recently launched advanced, tear-resistant composite bags designed for the transport of corrosive substances. Furthermore, the strategic acquisition of smaller regional manufacturers by industry giants demonstrates an ongoing consolidation phase aimed at scaling compliant, high-security packaging solutions to meet the growing demands of global industrial and waste management clients.